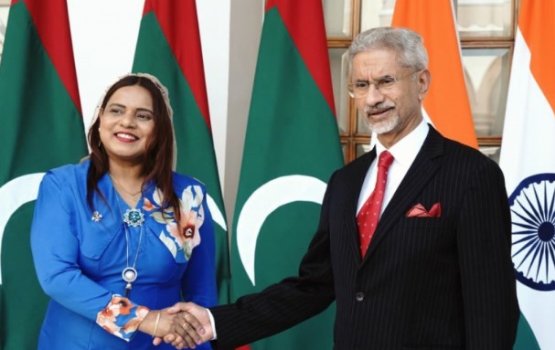

India has approved a rollover of a currency swap facility worth approximately USD 316 million to the Maldives, continuing financial support that has helped the country manage foreign exchange pressures and repayment obligations.
The Indian High Commission announced the decision on October 16, following a request from the Maldivian government. The facility was arranged between the Reserve Bank of India (RBI) and the Maldives Monetary Authority (MMA) under the SAARC currency swap framework, with the first withdrawal made on April 23, 2026.
The rollover allows the Maldives more time before repayment. It extends existing financing rather than providing an additional USD 316 million or cancelling the amount owed.
According to the High Commission, the rupee-denominated arrangement offers concessions on interest rates and other conditions. India described currency swaps and its subscriptions to Maldivian government securities as important instruments supporting the country’s financial stability.
Continued financial supportThe latest decision follows a series of Indian financial measures since 2024, including currency support, extensions of Treasury bill maturities and changes to loan repayment terms.
During President Dr Mohamed Muizzu’s state visit to India in October 2024, the RBI and MMA signed an agreement providing access to a USD 400 million swap and a separate rupee facility currently equivalent to approximately USD 316 million.
The Maldives settled the USD 400 million swap on April 23 this year, when India approved the first withdrawal under the rupee component. The Maldivian Foreign Ministry said the facility would support economic stability amid developments in West Asia.
India also extended the repayment periods of two USD 50 million Treasury bills in 2024, providing breathing space during a period of foreign exchange pressure. Further one-year extensions followed in May and September 2025.
Separately, agreements exchanged during Indian Prime Minister Narendra Modi’s July 2025 visit included a new line of credit currently equivalent to approximately USD 511 million for infrastructure and other activities.
An amendment to existing Indian government-funded credit arrangements also reduced annual repayment obligations under those facilities from approximately USD 51 million to USD 29 million. The measure eased the repayment schedule without writing off the underlying debt.
Debt originating under the previous governmentPart of the financial relationship involves obligations originating under former President Ibrahim Mohamed Solih’s administration.
In 2019, the Maldives obtained USD 150 million in budget support through three Treasury bills subscribed to by the State Bank of India (SBI). The current administration completed repayment with the final USD 50 million payment on September 17, 2026, according to the Finance Ministry.
The High Commission’s latest statement put India’s contribution towards interest on the settled Treasury bills at USD 42.8 million. That support was separate from the principal repaid by the Maldives.
Other borrowing during the Solih administration includes a USD 250 million bond purchased by SBI in 2020 to cushion the economic impact of the COVID-19 pandemic, and another USD 100 million bond purchased in 2022, according to the International Monetary Fund.
Those bonds are separate from the USD 150 million Treasury bill facility now cleared. India’s External Affairs Ministry said in September that SBI’s USD 350 million Treasury bond holdings run until 2029 and 2030.
The latest rollover continues a financial partnership spanning successive administrations, combining support for immediate liquidity needs with longer-term lending and development financing.